
Personal AI agents ruled at Money20/20. Banks will struggle to turn back the tide.

Top banks are blocking AI agents like Meta’s Muse. Taktile CEO & Co-founder Maik Taro Wehmeyer shares why the pause is reasonable, but could cost customers in the long-term.
Every booth in Vegas had the word “agentic” on it this year. But the busiest room I saw was a panel about Muse, Meta’s personal assistant. Every seat was full and people were standing in the aisles.
The energy around personal agents is driven by a shift in where the push for banks to adopt AI comes from. That pressure does not only sit with a bank’s C-suite or board anymore - it comes from customers who now have agents that can access their accounts and move their money. They want a new kind of experience, and they expect banks to make it possible.
Most big banks are blocking those agents today, and the pause is reasonable. But it isn’t a long-term strategy.
Jamie Dimon said the week before the conference that JPMorgan will not let outside agents log into customer accounts or move money. Citi, Bank of America and Schwab have taken the same position. On stage at Money20/20, Bill Demchak from PNC said no bank would let people transact without a human in the loop, and that he is “scared to death” of AI agent fraud.
I understand that concern better than most. I’ve spent over a decade building AI that powers banking decisions like how much to loan or whether a business is legitimate. In our industry, mistakes are incredibly expensive. So it is right to ask: why should a bank allow an unknown piece of software into the account before you know what it will do?
However, customers are setting the pace of AI adoption - and what they want is a simple, fast experience. Now it is for banks to figure out what they need to have in place to connect with personal agents safely.
Why blocking AI agents will cost banks customers
Consumers, which also means you and me, were the first to pick up AI in their daily lives and they are still the ones moving fastest. They set the new normal, and they are becoming fluent with AI agents for banking faster than anyone would have thought.
In a Forrester study for Experian, 54% of consumers said they are comfortable with an AI agent applying for credit on their behalf. 82% trust AI to compare loans across providers.
Imagine someone asks their agent to find them a $10,000 loan at the lowest cost, that can be in their account tomorrow. If the agent brings back offers from the lenders who collaborate with a personal AI agent like Muse, the banks that block it would not make the list. Market share would fall away rapidly.
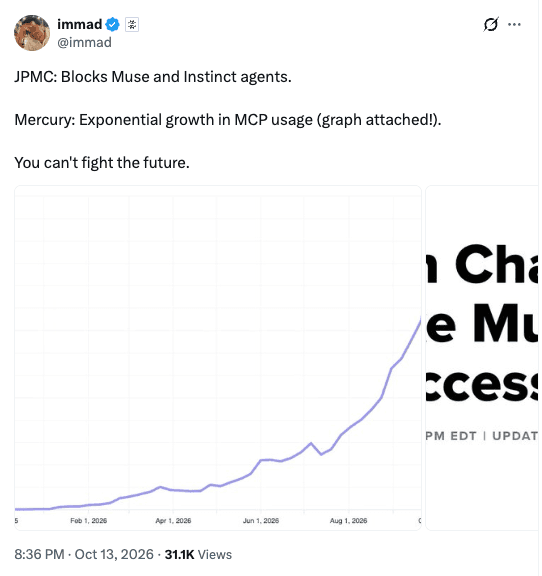
Banks risk missing out to more agile players. Mercury’s CEO Immad Akhund made an X post arguing that banks “can’t fight the future” when it comes to AI agents.
This shift in AI usage doesn’t only touch consumer banking. We could also see small businesses using AI agents to manage their accounts or apply for loans. Essentially, anywhere there is busy work that busy people would rather not do - they will expect a bank that can work with an AI agent who operates on their behalf.
AI safety has to run from the inside out
Banks are blocking outside agents like Muse because they cannot verify them or predict what they will do. But it’s a kind of paradox - because the AI agents banks are building themselves often have the same problem.
I spent most of Money20/20 talking to leaders who want to deploy AI agents in their credit, KYB, and onboarding decisions. Many of them do not yet have a way to govern those agents or monitor and optimize their impact on KPIs. It’s as if the black box is more visible from the outside than on the inside.
Here’s what I mean from an example at Taktile, where we’re building the infrastructure that enables banks and insurers to govern AI agents for every decision in one transparent layer.
A few months ago a bank we work with upgraded one of their credit agents to a new frontier model - and the accuracy of decisions dropped by about 30%. The model was not worse, the agent had just been tuned to the old version. If nobody had been monitoring the decisions in Taktile, that would have gone on for weeks, quietly impacting the P&L.
This invisible activity is the same issue that many banks are worried about with Muse. Except the bank would own the agent, and it sits inside their own lending or onboarding process. The answer isn’t to block the agent roll-outs. It’s to have a control tower for every decision an agent touches, and every action it takes.
This is what we built for Allianz Partners, and a lot of the learnings transfer to banking.
Their agents read claims documents in 60+ languages and check them against the policy, while expert adjusters still review the edge cases. The whole claims workflow runs on infrastructure where every claim has a full audit trail and the team can blend agents with deterministic rules to make sure policy is followed every time. Straight-through health claims went up 30% and adjudication quality improved 4-6%.
How banks will build at the speed customers demand
Customer expectations around using AI agents mean banks have to build their own AI infrastructure faster than they ever have. Which brings me to the other huge topic at Money20/20 - build vs. buy.
What I heard from leaders is that AI feels so easy in everyday life, building your own agentic stack feels like it should be easy too.
It might be simple for a consumer to apply for loans with an agent. But it is not easy for a bank to coordinate agents, policies and countless data sources to decide how to respond.
One bank we work with had an agent ready in two weeks, then spent months wiring it into the credit workflow and the legacy systems around it. And that wiring is never finished - models change every few months, and regulations change. If your credit team is maintaining infrastructure instead of watching how the portfolio performs, you lose grip on what actually gives you an edge.
No bank writes its own database or runs its own payment rails from scratch. They own what makes them different - the credit policy, the data, and the risk appetite - and they build on top of something proven.
So my answer to the build vs. buy question is that it is the wrong question. Build your agents, they carry what your bank knows that nobody else does. But buy the map they stand on, so the next use case takes days and not months, and the people who own the decision can see what is happening the whole time.
We can’t take power back from consumers
Customers set the pace of change in banking, and now they have agents that can shop for a loan or a better rate on their behalf. A bank can block that agent today but it cannot block the expectation behind it.
So the pause makes sense, as long as it is used well. Build your own agents, because they hold what only your bank knows. Then run them on infrastructure where your teams can see what every agent decided and why, and step in when something moves. That is what makes it possible to say yes or no to the customer’s agent when the time comes, fast and safely.
One thing that is for sure - the banks with the full house at their panels at the next Money20/20 will be the ones who meet this moment.