
How to automate SMB credit underwriting: from application to credit decision
LendingSep 15, 2026
Automating SMB credit underwriting means using software to collect and verify borrower data, analyze financials, apply credit policy, assess risk, and route applications to the appropriate decision path. A modern workflow combines data integrations, deterministic rules, risk models, AI agents, and human review. Straightforward applications can be processed automatically, while ambiguous, complex, or high-risk cases are escalated to an underwriter.
Key takeaways
- Automation does not mean removing human underwriters. The strongest approach combines rules, risk models, AI agents, and human review so complex or uncertain cases still receive expert judgment
- Financial spreading is increasingly suitable for AI-assisted automation. Taktile Labs’ FinSpread-Bench found that the strongest tested configurations exceeded an approximately 89% human field-match baseline.
- The goal is not 100% automation. Lenders should automate repeatable work while keeping controls, traceability, and human review in place for decisions that require judgment
What does SMB credit underwriting automation actually automate?
SMB credit underwriting automation replaces repetitive manual work across the underwriting process rather than simply automating the final approve-or-decline decision.
Tasks that can be automated include collecting application data, checking whether required documents are present, retrieving third-party data, verifying business information, spreading financial statements, calculating financial ratios, applying credit policy, preparing decision summaries, and routing exceptions.
Human underwriters remain important when a decision requires interpretation, policy exceptions, unusual accounting treatment, or judgment that cannot be reduced to a predefined rule or model.
The objective is therefore not maximum automation. It is to minimize manual work that does not require human judgment.
How does an automated SMB underwriting workflow work?
An automated SMB underwriting workflow typically moves through seven stages from application intake to credit decision.
| Stage | What happens | Typical automation |
|---|---|---|
| Application intake | Business, applicant, and financing data are captured and checked for completeness | Workflow automation and validation rules |
| Business verification | Business identity, ownership, registrations, and fraud signals are checked | KYB providers, data integrations, rules |
| Data collection | Credit, bank, accounting, financial, and internal data are retrieved | APIs and data integrations |
| Financial analysis | Financial statements are extracted, standardized, and analyzed | Document parsing and financial spreading agents |
| Risk and policy assessment | Eligibility criteria, financial ratios, scores, and risk thresholds are evaluated | Rules engines and risk models |
| Exception routing | Ambiguous or high-risk applications are escalated | Confidence thresholds and case management |
| Credit decision | The application is approved, declined, or referred and the decision is documented | Decision engine plus human approval where required |
Each stage can be fully automated, assisted by technology, or handled manually depending on the lender's credit policy, product, loan size, risk appetite, and borrower complexity.
1: Automate application intake and completeness checks
The first step is converting a credit application into complete, structured, decision-ready information.
An automated workflow can validate required fields, check whether the necessary documents have been submitted, identify inconsistent information, and prevent incomplete applications from reaching an underwriter.
For example, the workflow can verify that required financial statements cover the correct reporting periods and check whether the business name, requested amount, ownership information, and submitted documents are consistent.
Automating these checks prevents underwriters from spending time preparing files or repeatedly requesting missing information before they can begin assessing credit risk.
2: Verify the business and applicant
Automated business verification confirms that the applicant and business match the information provided in the application.
Depending on the lender and jurisdiction, this can include corporate registry data, Know Your Business (KYB) checks, identity verification, ownership data, business credit information, sanctions screening, fraud signals, and internal customer records.
Automation is particularly useful when information must be compared across sources. A legal name, registered address, or owner that does not match external records can automatically trigger further review, while consistent applications continue through the workflow without manual investigation.
3: Collect the data required for the credit decision
Automated underwriting brings the data required by the lender's credit strategy into one decision workflow.
Common inputs include:
- application data
- business credit information
- personal guarantor data where applicable
- bank transactions and cash-flow data
- accounting platform data
- income statements and balance sheets
- tax documents
- payment history
- industry data
- the lender's internal customer data
The right data depends on the product. A working-capital lender may place greater weight on recent cash flow, while underwriting a larger commercial facility may require multiple years of financial statements and additional qualitative assessment.
The credit strategy should determine which data is used, rather than the availability of a data source determining the credit strategy.
4: Automate financial spreading and analysis
Financial spreading converts financial statements into standardized data that can be used for credit analysis.
The process requires more than extracting numbers from a PDF. An underwriting system may need to align reporting periods, map different accounting labels into a standard schema, calculate missing values, interpret financial-statement notes, and apply institution-specific conventions.
Taktile Labs' FinSpread-Bench, published in March 2026, evaluates AI systems on financial spreading using 1,312 fields across 84 documents based on real underwriting cases. The benchmark reports an approximately 89% human field-match baseline. The highest-performing tested configuration, GPT-5.2 with Gemini 3.1 Pro for document extraction, achieved 96.5%. Gemini 3.1 Pro achieved 95.9%, while Claude Opus 4.6 achieved 94.3%.
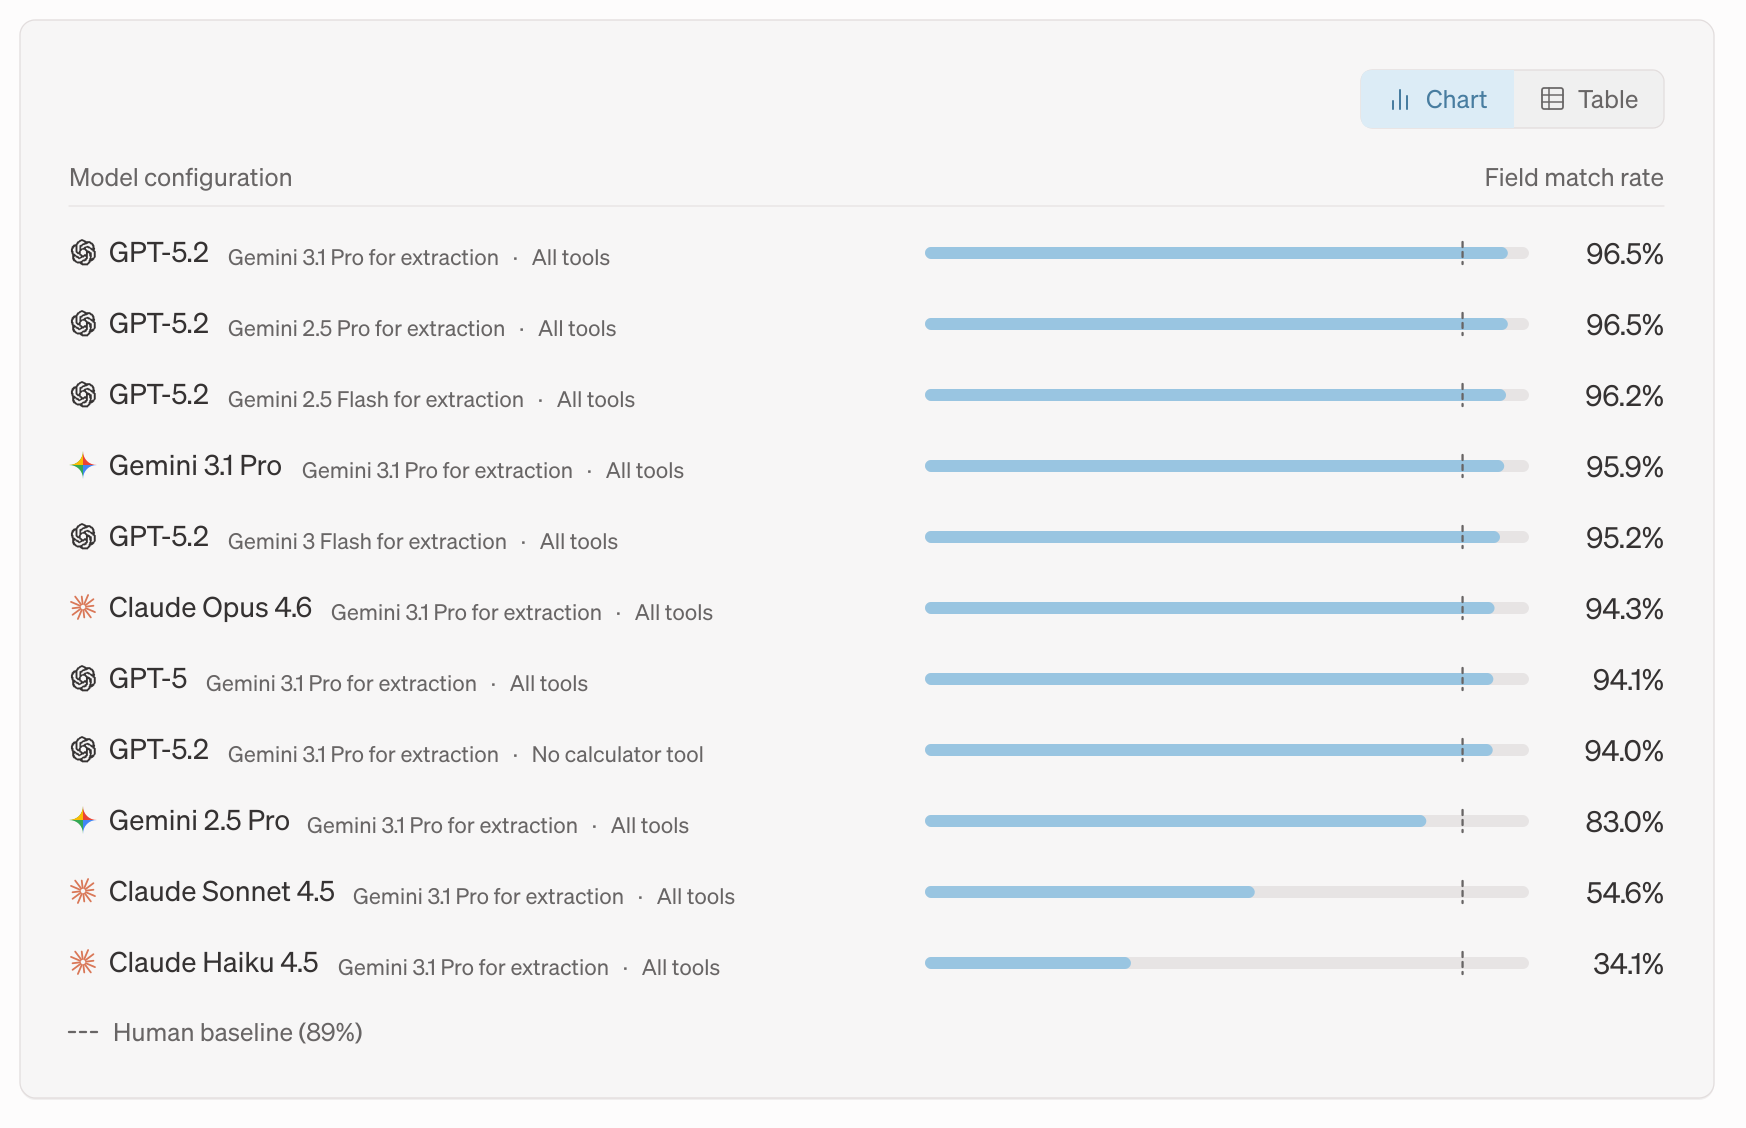
The same benchmark shows why model selection matters. Taktile Labs found that the strongest configurations' remaining errors were dominated by reasoning, mapping, and institution-specific convention errors, such as how debt should be classified, rather than simple number extraction.
This makes financial spreading a good candidate for automation with exception handling: high-confidence outputs can proceed automatically, while ambiguous classifications or unusual accounting treatments can be reviewed by an underwriter.
5: Apply credit policy, risk models, and decision rules
Once the required data has been collected and standardized, the lender can automatically evaluate the application against its credit strategy.
A workflow might assess minimum eligibility criteria, credit bureau thresholds, leverage, debt-service coverage, cash flow, industry restrictions, fraud results, exposure limits, proprietary scores, and pricing models.
Different technologies play different roles:
| Component | Best suited for |
|---|---|
| Data integrations | Retrieving the information needed to make the decision |
| Deterministic rules | Explicit eligibility criteria and policy thresholds |
| Statistical or machine-learning models | Quantifying default, loss, or other risk |
| AI agents | Documents, research, qualitative analysis, and summaries |
| Human underwriters | Exceptions, ambiguity, and judgment-heavy decisions |
Automated SMB underwriting does not mean letting one AI model make the entire credit decision. Taktile combines rules, risk models, AI agents, and human review, so straightforward cases can move automatically while more complex or uncertain decisions stay with an underwriter.
6: Route exceptions to human underwriters
Human-in-the-loop underwriting uses automation to determine which applications actually require expert review.
A case can be referred to when information conflicts across sources, an application sits close to a policy threshold, an AI output has low confidence, the requested exposure exceeds defined limits, or the borrower requires a policy exception.
One Taktile customer using AI-assisted underwriting reported cutting credit underwriting time by 50% while keeping human experts responsible for final credit decisions. The company also automated 80% of onboarding tasks and tripled its onboarding capacity.
The purpose of human-in-the-loop underwriting is therefore not to insert manual review into every automated workflow. It is to concentrate human expertise on the cases where judgment can change the quality of the decision.
7: Make and document the credit decision
The final stage converts the underwriting result into an approve, decline, or review outcome and records how that result was reached.
An automated workflow can generate the proposed credit amount and terms, relevant calculations, reason codes, decision summary, and supporting case documentation. It should also preserve which data, rules, models, AI outputs, and human overrides contributed to the result.
Maintaining this decision history makes automated outcomes easier to review, explain, and audit.
What results can SMB underwriting automation deliver?
Common operational goals of SMB underwriting automation are higher processing capacity, faster decisions, and less manual work.
Breakout Finance, a U.S. B2B lender, reported an up to 95% reduction in underwriting time, taking decisions from one hour, and in some cases up to four hours, to as little as three minutes after implementing Taktile. Breakout Finance also reported capacity to process three to five times more applications.
These are vendor-reported customer results rather than universal industry benchmarks. Lenders should measure automation against their own decision time, manual-review rate, applications processed per underwriter, approval rate, override rate, portfolio performance, and credit losses.
How much of SMB credit underwriting should be automated?
The right level of automation depends on the risk and complexity of each application.
One practical way to structure SMB underwriting automation is around three decision paths:
- Straight-through decisions: Complete applications with clear outcomes under the lender's policy proceed automatically
- Technology-assisted decisions: Automation collects data, analyzes documents, calculates metrics, and prepares the case while an underwriter confirms the final decision
- Expert-led decisions: Complex, high-value, unusual, or exception cases receive deeper human analysis.
The appropriate target is not 100% automation. It is the lowest level of manual work consistent with the lender's risk appetite, credit performance, customer experience, and governance requirements.
How should lenders start automating SMB credit underwriting?
Lenders should begin with tasks that consume substantial analyst time but require limited expert judgment.
A practical sequence is:
- Map the existing underwriting process and identify bottlenecks
- Measure how much analyst time each step requires
- Automate repetitive tasks such as document checks, data retrieval, spreading, and calculations
- Connect the internal and external data required by the credit strategy
- Codify eligibility criteria, thresholds, models, and escalation rules
- Define which cases can proceed automatically and which require human review
- Test the workflow against historical applications before production
- Monitor decision quality, manual-review rates, overrides, credit performance, and data quality after launch
Automation can then expand as observed performance demonstrates that additional tasks or decisions can be handled reliably.
Frequently Asked Questions (FAQs)
Yes. Standardized, data-rich applications with clear outcomes under a lender's credit policy can be processed without manual review, while complex, high-value, or exception cases are better suited to human-in-the-loop underwriting.
Automated underwriting is the broader category and can combine data integrations, rules, risk models, workflow automation, and human review. AI underwriting adds machine-learning models or AI agents for tasks such as document interpretation, financial spreading, research, and summarization.
Financial spreading is the process of converting financial statements into a standardized format for credit analysis. Taktile Labs' FinSpread-Bench found that several frontier AI configurations exceeded its approximately 89% human field-match baseline on this task.
Not necessarily. Automation handles repetitive work such as data retrieval, document checks, financial spreading, calculations, and policy rules, while analysts remain important for exceptions, complex exposures, and decisions requiring judgment.